Money Management App Essentials for 2026: Control Your Cash on the Go
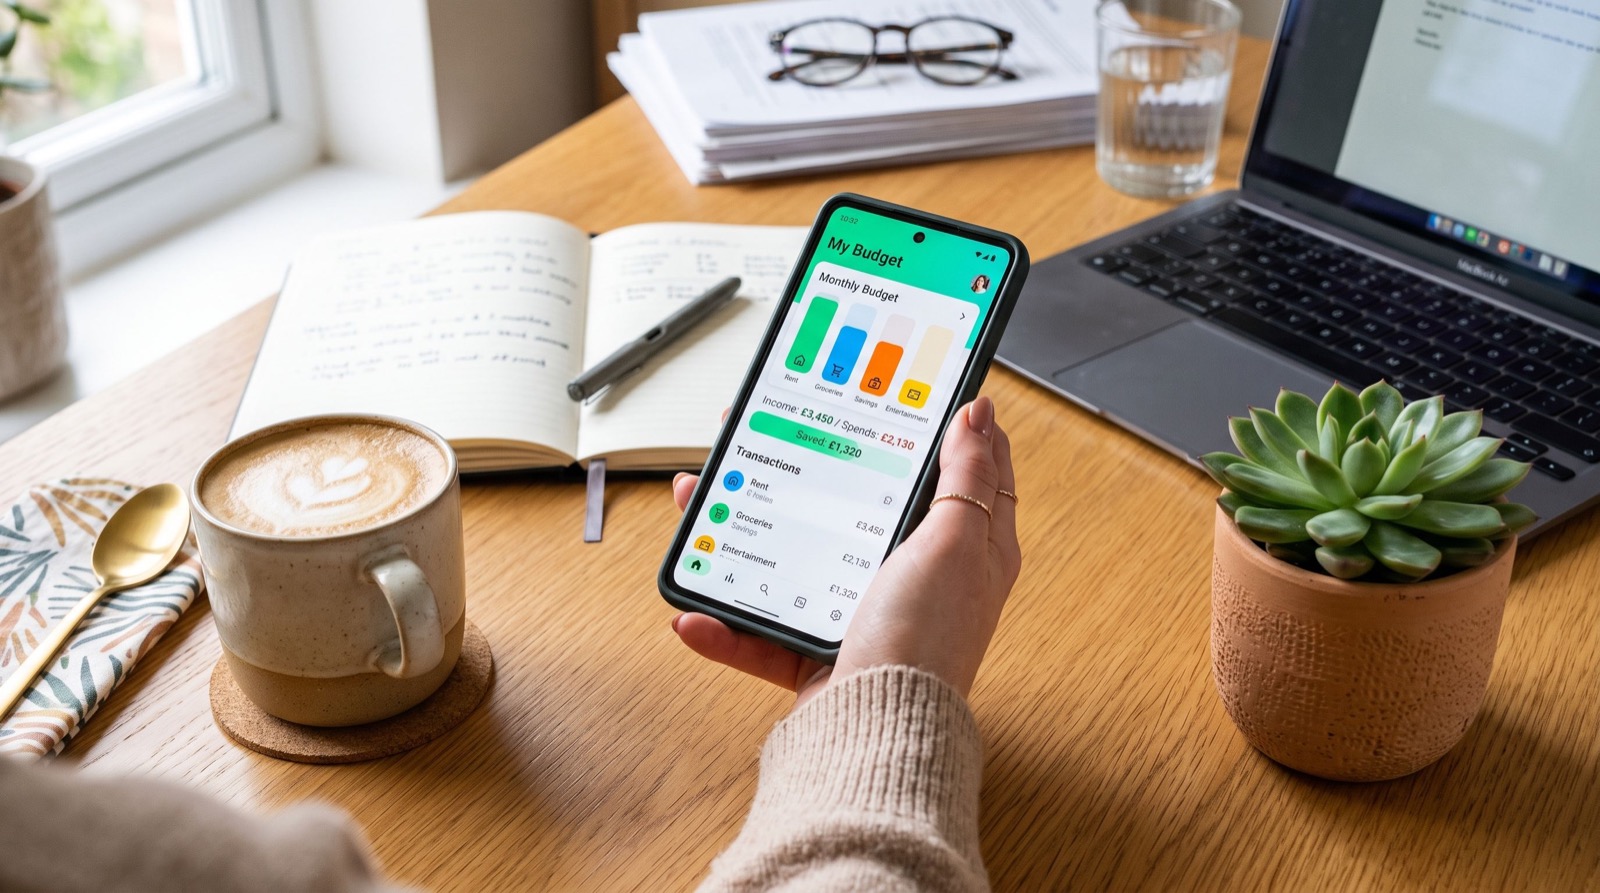
Choosing the right money management app can turn a chaotic financial life into a calm, automated one. In 2026, your phone doubles as a bank branch, a budgeting coach, and a payment terminal. The trick is picking tools that simplify decisions instead of piling on more notifications and dashboards to ignore.
This guide explains what a great money management app should do, how to combine budgeting with fast payments, and how to protect every dollar you move. Whether you are relocating, launching a side hustle, or just tired of financial guesswork, these principles apply.
What a Modern Money Management App Should Do
The best tools share a short list of core jobs. They connect to your accounts, categorize spending automatically, forecast upcoming bills, and nudge you toward better habits. Anything beyond that is a bonus, not a requirement.
Prioritize clarity over complexity. A dashboard you check daily beats a feature-packed platform you open twice and abandon. When a money management app makes your next decision obvious, it is doing its job.
Core Features Worth Demanding
- Automatic categorization so you see where money truly goes.
- Bill forecasting that warns you before cash runs low.
- Goal tracking for savings targets and debt payoff.
- Real-time alerts for unusual or large transactions.
- Bank-level security with encryption and biometric access.
Pairing Budgeting With Fast Payments
Tracking spending is only half the equation. You also need a frictionless way to move money. Peer-to-peer payment tools handle rent splits, reimbursements, and quick sends in seconds. If you are new to these, this practical Cash App guide covers safe sending, fees, and features worth knowing.
The winning combination is simple: one app to see your full picture and one app to move money quickly. Together they cover both awareness and action, which is where most budgets succeed or fail.
Why the Combination Matters During Big Transitions
Life changes strain finances. Moving, changing jobs, or furnishing a new home creates a flurry of one-off costs. Working with reliable local experts during a move helps you plan the logistics, while a solid app stack keeps the money side under control when spending spikes.
How Do You Choose the Right App?
Match the tool to your biggest weakness. Overspenders need strict budgeting features. People who lose track of subscriptions need recurring-charge detection. Those saving for a goal need visual progress tracking that keeps motivation high.
Test each candidate for at least two weeks. Free trials reveal whether the interface fits your routine. If checking the app feels like a chore, it will not stick, no matter how powerful the feature list looks on paper.
Comparing App Types by Strength
The table below shows how different app categories serve different needs, so you can build a stack that covers your gaps.
| App Type | Greatest Strength | Ideal User | Cost Range |
|---|---|---|---|
| All-in-one budgeting | Full financial picture | Overspenders | Free–$15/mo |
| Peer-to-peer payments | Instant transfers | Bill splitters | Free |
| Automated saving | Effortless deposits | Goal savers | Free–$5/mo |
| Investing platforms | Long-term growth | Beginners | Free–0.25% AUM |
Building Habits Around Your Tools
An app is only as good as the routine around it. The most successful users pair their tools with a handful of simple, repeatable actions. Adopting these personal finance tips turns your money management app from a passive tracker into an active coach.
- Review your dashboard every Sunday for ten minutes.
- Automate savings transfers on payday before spending starts.
- Set alerts for any transaction over a threshold you choose.
- Cancel one unused subscription each month.
- Reconcile large purchases against your goals before committing.
Security You Should Never Skip
Linking financial accounts demands strong protection. The Federal Deposit Insurance Corporation publishes clear guidance on how insurance applies to digital financial products, and trustworthy apps make that information easy to find.
Enable two-factor authentication, use a unique password, and turn on biometric login everywhere possible. Never store more cash in a payment app than you need for near-term spending. Insured savings accounts remain the safest home for money you plan to keep.
Warning Signs to Watch For
- Apps requesting permissions unrelated to finance.
- Vague or hidden fee schedules.
- No clear customer support channel.
- Missing regulatory or insurance disclosures.
Setting Up Your App Stack Step by Step
Assembling the right tools does not have to be overwhelming. A short, deliberate setup gets you running in an afternoon and pays dividends for years. Follow this sequence to build a stack that covers awareness, action, and growth.
- Choose one budgeting app and connect every account for a full picture.
- Add one payment app and complete identity verification for higher limits.
- Set up automated transfers to a high-yield savings account on payday.
- Enable alerts and biometric security across every connected tool.
- Schedule a recurring weekly review to keep the system honest.
Resist the urge to install everything at once. Each new app adds cognitive load, so introduce one tool, build the habit, then layer in the next only when the first feels effortless.
Common Setup Mistakes to Avoid
- Linking accounts but never reviewing the dashboard.
- Storing large balances in payment apps instead of insured accounts.
- Ignoring security prompts to save a few seconds at login.
- Chasing new apps before mastering the ones you already have.
Avoid these traps and your money management app becomes a quiet, reliable partner. The goal is a system so smooth that good financial decisions happen almost automatically.
Frequently Asked Questions
What is the best money management app for beginners?
The best one is the app you will actually open daily. Beginners usually benefit from a simple budgeting tool with automatic categorization, paired with one payment app for quick transfers and bill splitting.
Do I need more than one finance app?
Often yes. Most people use one budgeting app for visibility and one payment app for action. Add a saving or investing tool only once those two are working smoothly in your routine.
Are money management apps secure?
Reputable apps use bank-level encryption, two-factor authentication, and biometric locks. Security also depends on you: enable every protection, use unique passwords, and avoid storing large balances in payment apps.
How often should I check my finance app?
A quick daily glance plus one deeper weekly review works well. Frequent, low-stress check-ins catch problems early and keep your budget aligned with your goals without causing burnout.
Final Thoughts and Your Next Step
A money management app is the backbone of modern personal finance, but only when paired with smart habits and strong security. Choose tools that simplify your decisions, combine budgeting with fast payments, and protect every account you connect.
Start today by picking one budgeting app and one payment tool, then commit to a ten-minute weekly review. In 2026, financial control is not about willpower; it is about building a system that quietly works for you around the clock.